A free review can never hurt.
Now you can get anywhere up to 40% reduction on your monthly premiums
Suspendisse interdum consectetur libero id. Fermentum leo vel orci porta non. Euismod viverra nibh cras pulvinar suspen.
Blogs
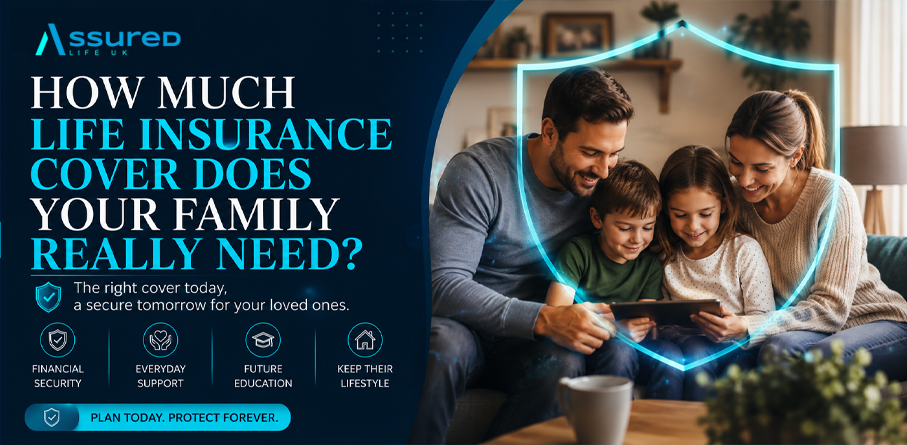
How Much Life Insurance Cover Do I Need in the UK?
.webp)
Life insurance is designed to give financial assistance to your loved ones should you die during the term of the policy. But it’s not always simple to work out how much cover you truly need. It is contingent upon your income, mortgage, obligations, savings, family commitments and future financial objectives. How much life insurance do I need in the UK? Life insurance can offer a lump amount to loved ones, says Assured Life UK, but cover should be matched to individual circumstances, preferences and requirements.
Begin With Your Family’s Financial Needs
The first question to ask yourself is, who depends on your salary and financial support? If you are no longer able to provide your earnings, a spouse or partner, dependent children or other family members may face major financial upheavals. Therefore, regular household expenses, childcare, education and everyday living costs should be taken into account when evaluating the amount of protection needed. The aim is to create a financial safety net, which will allow your dependents to meet future responsibilities without undue strain on their finances.
Your present wage is a good baseline, but applying a set amount to your salary doesn’t necessarily give you an exact number. Rather, use this simple formula, examine how much money your family would truly require and for how long. Think about your family situation – the ages of your children, your partner’s earnings, what you already have saved and any other financial resources you have. A tailored assessment like 10x annual income rule life insurance can help you decide a suitable level of cover, rather than using a conventional figure.
What Financial Obligations Should You List?
Your Life insurance calculation formula UK should include a large part for your outstanding bills. For a household, a mortgage might be one of the biggest financial commitments over the long term. If you die before the mortgage is paid off, depending on the ownership arrangements and other conditions, your family may still have to cover the repayments. Mortgage protection can be arranged in a number of ways, so when considering how much cover may be appropriate, it's necessary to think about the balance, repayment plan and type of policy.
Other debts should also be taken into account when you examine your protection needs. Personal loans, credit commitments and other liabilities might diminish the money available to your family after your death. Costs of funerals may also need to be taken into account, particularly where there is little in the way of savings. Assured Life UK says that life insurance could be a good idea if you don’t have enough saved up to pay off your debts or cover funeral expenses.
Consider Your Existing Savings and Protection
Consider your current financial situation when you select a policy amount. Existing life insurance, savings, occupational benefits and other assets can help provide for your family's financial security. These resources may help you reduce the amount of extra cover needed. But it’s worth understanding what your old policies actually offer, when they pay out and if the insurance is still appropriate for your present circumstances.
Protection that exists today should not be considered to be adequate indefinitely. Your income, mortgage, family situation and Tax-free lump sum payout UK can change over time. Assured Life UK recommends that you assess your current policy to see if it is still appropriate, the level of protection is sufficient and that you are not overpaying. Regular evaluations can uncover gaps that may arise from major changes in your financial status.
Evaluate How Much Time You Need Coverage
How long your policy is in force is as crucial as the amount insured. Most people get cover for the years when their financially dependent loved ones depend most on them. For instance, parents might desire coverage until their kids are expected to be financially independent. Alternatively, a person with a mortgage may want a policy term that matches the remaining time on the mortgage and the payback responsibilities.
There are several sorts of coverage under different types of life insurance. Level period insurance ensures that the sum assured remains at the same level across the policy period. Decreasing term insurance usually relates to repayment mortgages, where the amount of cover reduces over time. Inflation-linked insurance can increase the sum assured in pace with inflation, helping to offset the potential decline in the real value of protection.
Consider your financial objectives for the future
Life insurance should be considered as more than a shield for existing liabilities. If you have no income, your family may have future financial objectives that could be impacted. The role can entail caring for children, running a household, caring for a partner or other long-term commitments. By considering these prospective expenditures you can get a more realistic idea of the level of security your family may need.
Simultaneously, selecting more insurance than is necessary can result in a higher premium without offering any significant additional benefit for your circumstances. The goal is to reach a workable compromise between adequate financial protection and a reasonable premium. Assured Life UK says the available options on the insurance and the cost are dependent on a number of criteria and cover may be tailored around individual needs and budgets.
Do you need to consider more than just basic life cover?
Life insurance is one example of financial security. Depending on your circumstances you may also want to consider products like critical sickness cover, income protection, mortgage protection or family income benefit. These products are for different purposes and should not be considered equivalent. For example, Family Income Benefit pays a monthly income for the rest of the policy term after a successful claim, rather than offering the same sort of lump payment as ordinary life cover.
The optimal balance will depend on your unique financial situation and protection goals. Some may need solely to protect their family, others will need to think about a mortgage, dependants or income related hazards. Understanding the distinctions between these products will help you determine the type and amount of protection you need. Professional guidance from FCA authorised life insurance adviser might also be useful when there are a number of policy options being explored.
Conclusion
There’s no one-size-fits-all quantity of life insurance. To calculate how much life insurance you need, the amount of protection you require will depend on your family’s financial commitments, mortgage, debts, savings, income and how long you may need to provide for your dependents. Look at these aspects together, and reassess them when your situation changes, rather than picking a random number. Assured Life UK provides access to FCA-authorised advisers who can explain the options available and help you make an informed decision depending on your circumstances. Call Assured Life UK immediately to discuss your protection needs, know about the DIME method for life insurance UK, explain your life insurance alternatives and choose a policy to suit your family’s financial demands and budget.
FAQs
How much life insurance do I need?
This relies on your income, bills, mortgage, savings, dependants and future financial commitments.
How does a mortgage impact my life insurance needs?
Yes, the level of protection you require should take account of your mortgage balance and repayment plans.
Do I need to examine my life insurance plan?
Yes, it’s a good idea to do Whole-of-market life insurance comparison when your financial or family situation changes to make sure it’s still appropriate.

Assured Life UK
Meet Our Founder
Assured Life UK connects customers with trusted, FCA-authorised insurance advisers, helping over 50,000 people find the right cover without overpaying. Founded by Sumit Kapoor, who brings around 16 years of life insurance experience alongside earlier stints in motor insurance and mortgage broking, the company is built on honesty, integrity and putting clients' needs ahead of commissions.
TRENDING POST




RECENT POSTS
.webp)
.webp)
How Much Life Insurance Cover Do I Need in the UK?
Sep 17, 2026.webp)
Do I Need Life Insurance if I Have No Dependants?
Sep 16, 2026
NEWSLETTER
Subscribe my Newsletter for new blog posts. Stay updated from your inbox!
Leave a Comments